Receiving a significant work bonus or unexpected financial windfall often brings a rush of excitement and anticipation. You suddenly have extra cash sitting in your bank account, and the urge to spend it on luxury items is understandably strong. However, learning how to use a work bonus or windfall to pay off debt faster provides a significantly higher long-term return on your investment.
Paying down high balances immediately stops the brutal cycle of compound interest and drastically improves your monthly cash flow. Every dollar you owe to a creditor represents a claim on your future earnings and restricts your financial freedom. By prioritizing debt elimination, you take immediate control of your financial trajectory and build a foundation for lasting wealth.
Redirecting a bonus toward liabilities requires substantial discipline, but the mathematical benefits are impossible to ignore. You will save thousands of dollars in future interest charges while simultaneously reducing your daily financial stress. This comprehensive guide will explain exactly how to deploy your extra cash to achieve the maximum financial impact.
Behavioral economists have studied how humans treat sudden cash infusions and unexpected windfalls for several decades. They found that people frequently fall victim to a psychological cognitive bias known as mental accounting. We tend to view a regular paycheck as serious money, while treating a corporate bonus as disposable income meant for splurging.
This psychological trap keeps millions of Americans stuck in a frustrating cycle of revolving credit card balances. According to the Federal Reserve Bank of New York, total consumer credit card debt in the United States recently surpassed $1.1 trillion. If you treat your hard-earned bonus as found money, you miss a massive opportunity to improve your overall net worth.
You must actively reframe how you view this extra income to make truly objective financial decisions. Think of your windfall as a powerful tool to literally buy back your future time and freedom. By eliminating high-interest balances today, you permanently lower your monthly expenses and heavily reduce your financial anxiety.
- Mental accounting tricks us into spending bonuses frivolously instead of paying off serious debts.
- Reframing a windfall as an investment in your future freedom helps maintain financial discipline.
- Paying off debt offers a guaranteed return on investment by eliminating future compound interest charges.
How to Use a Work Bonus or Windfall to Pay Off Debt Faster: Assess Your Financial Picture
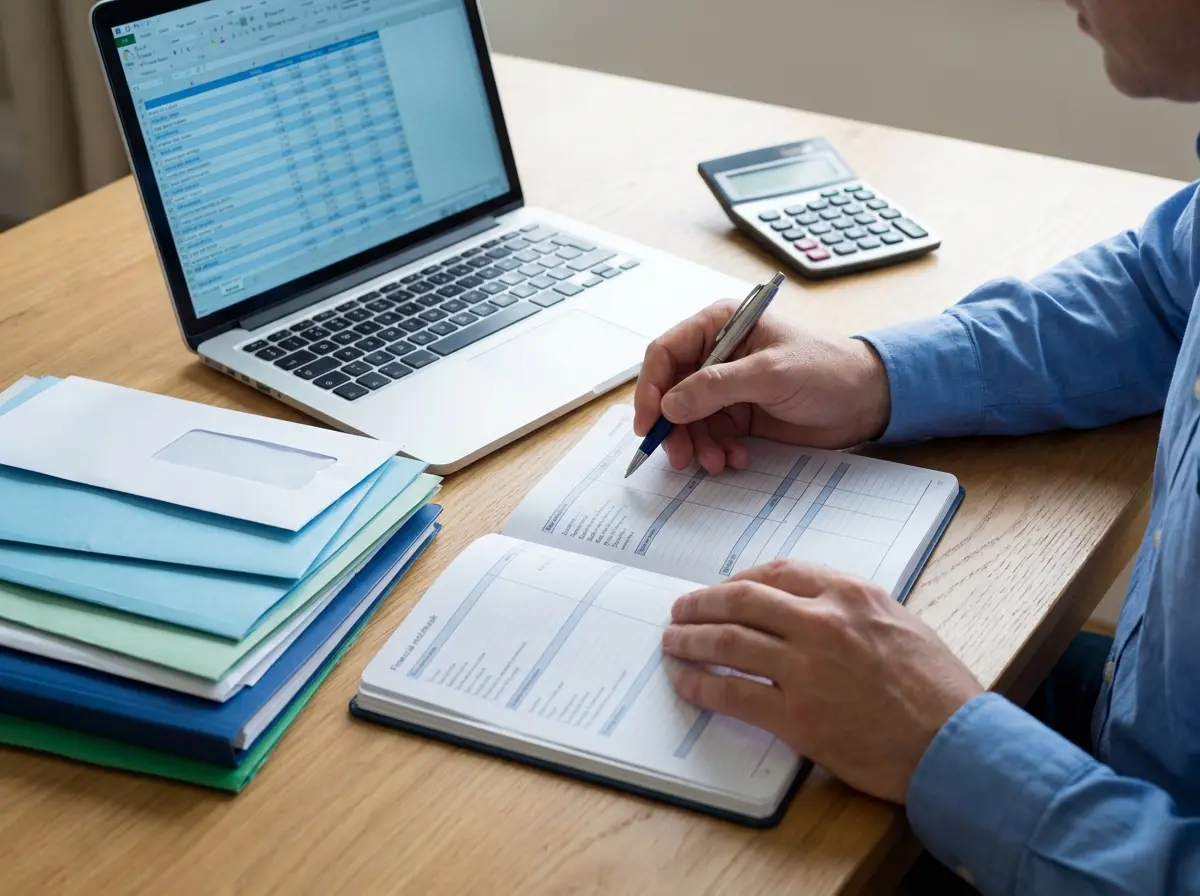
Before you transfer a single dollar to a creditor, you need a complete understanding of your current liabilities. Gather every recent statement for your credit cards, student loans, auto loans, and personal lines of credit. Create a simple spreadsheet listing the specific creditor, total balance, minimum monthly payment, and the annual percentage rate.
This organizational process forces you to confront the absolute reality of your current financial situation. Many people actively avoid looking at their total numbers because the aggregate sum feels intimidating. However, you need this hard data to make highly mathematical decisions about where your bonus will do the most good.
Reviewing these statements also highlights exactly how much money you throw away on interest charges every month. Seeing a $200 monthly interest charge on a single credit card usually provides excellent motivation to change your habits. Using a personal net worth tracker can help you visualize this progress as you pay down those balances.
Work Bonus Tax Implications: Understanding the Net Value of Your Income
You also need to calculate the actual net amount of your bonus before making any grand plans. Employers typically withhold taxes on bonuses at a flat supplemental rate, which differs from your standard paycheck. In the United States, the Internal Revenue Service currently mandates a 22 percent federal withholding rate for supplemental wages.
State taxes, Social Security contributions, and Medicare deductions will also take a significant bite out of the gross amount. A $10,000 bonus on paper might only translate to $6,500 of actual cash deposited into your checking account. Do not make aggressive payment plans based on the gross bonus number, or you will end up financially short.
If your employer lumps the bonus into your regular paycheck, it might push you into a higher withholding bracket temporarily. You will eventually get any overpaid taxes back when you file your annual return next spring. However, for immediate debt payoff purposes, you must deal strictly with the cleared cash sitting in your bank account.
Never commit to paying a specific debt amount until the bonus funds have fully cleared your checking account. Estimated tax withholdings can vary widely, leaving you with less cash than you initially projected.
Evaluate High-Interest Credit Card Debt and Other Financial Liabilities
Not all debts carry the same level of financial urgency or impact on your overall wealth. High-interest consumer debt, like credit cards and payday loans, should always be your absolute highest priority. These toxic liabilities compound rapidly and can easily trap you in a permanent cycle of minimum payments.
Mid-interest debts, such as personal loans or older auto loans, usually carry interest rates between seven and twelve percent. While not as financially devastating as credit cards, they still represent a significant drag on your monthly budget. Clearing these balances with a windfall frees up substantial cash flow that you can redirect toward productive investments.
Low-interest debts, like fixed-rate mortgages or subsidized student loans, generally do not require aggressive early payoff strategies. If your mortgage rate sits at three percent, mathematically, you are better off investing your bonus in the stock market. You can easily earn a higher average return through an index fund than you save by paying off cheap debt.
Select an Effective Debt Payoff Strategy for Your Financial Windfall
Financial experts generally recommend two primary strategies for eliminating debt: the avalanche method and the snowball method. The avalanche method focuses strictly on mathematics by attacking the balance with the highest interest rate first. You continue making minimum payments on everything else while throwing your entire windfall at the most expensive liability.
This highly mathematical approach saves you the maximum amount of money in interest charges over time. If you have a credit card charging 24% APR and a car loan at 6%, clearing the credit card offers a guaranteed 24% return. You will struggle to find any traditional investment that provides a completely risk-free return matching those exorbitant credit card rates.
The snowball method takes a fundamentally different approach by focusing heavily on human psychology and personal motivation. You order your debts from the smallest balance to the largest, completely ignoring the interest rates attached to them. You apply your bonus to wipe out the smallest accounts first, giving yourself an immediate psychological victory.
Evaluating the Math vs. Emotion Dilemma
Choosing between these two distinct methods depends heavily on your personality and specific financial goals. If you possess strict financial discipline, the avalanche method makes the most logical sense for your portfolio. You will reach a zero balance faster and keep significantly more of your hard-earned money in your own pocket.
However, behavioral studies published by the Harvard Business Review show that the snowball method often leads to higher long-term success rates. The quick wins provide a powerful surge of dopamine that keeps people motivated to stick with their payoff plans. If you have multiple small balances cluttering your mind, wiping them out with a bonus feels incredibly satisfying.
You can also create a hybrid approach if your windfall is large enough to cover multiple accounts. You might use a portion of the bonus to clear two small, annoying debts for the psychological win. Then, you can route the remainder of the funds directly toward your highest-interest credit card balance.
Step-by-Step Guide to Applying Your Windfall for Debt Reduction
Having a concrete action plan prevents you from accidentally spending your bonus on impulsive luxury purchases. You need to create deliberate friction between your new cash and your typical daily spending habits. Follow this structured procedural process to apply your funds effectively and guarantee the money goes exactly where intended.
How to Execute Your Payoff Plan
Park the Cash in a Separate Account
Move the money to a high-yield savings account at a different bank immediately after it clears. This completely removes the temptation to spend it while you formulate your official payoff strategy.
Request Official Payoff Quotes
Contact your lenders directly to request an exact payoff quote valid for the current date. Interest accrues daily, so your previous monthly statement balance is likely outdated and inaccurate.
Execute the Payments Promptly
Log into your financial accounts and submit the manual payments directly to the principal balances. Do not wait for the next billing cycle to process these critical transactions.
Strategic Negotiation Tactics for Collections and Debt Elimination
If you have older debts that have fallen into third-party collections, a lump sum bonus gives you incredible negotiation power. Collection agencies typically buy bad debt from original creditors for literal pennies on the dollar. Because their cost basis is so low, they will very often accept a significantly reduced payoff amount.
You can call the collection agency and offer them a percentage of the total balance in exchange for closing the account. Start by offering twenty-five percent of the total balance, and negotiate upward until you reach an agreeable settlement. Make sure you get the final settlement agreement in writing before you transfer any funds from your bonus.
You should also attempt to negotiate how the settled account will report on your credit file moving forward. The best possible outcome is a “pay for delete” agreement, where the agency removes the negative mark entirely. If they refuse, insist that they report the account as “Paid in Full” rather than “Settled for Less.”
Never give a collection agency direct electronic access to your main checking account. Pay negotiated settlements using a cashier’s check or a separate, temporary bank account to protect your remaining funds.
Balancing Debt Payoff With Emergency Funds and Savings
Sometimes, throwing your entire bonus at a single credit card is not the most optimal move for your overall security. You might benefit significantly from splitting the funds across a few different pressing financial priorities. If you completely lack emergency savings, you should strongly consider keeping a portion of the windfall in cash.
Paying off a massive credit card balance feels great, but it leaves you vulnerable if an unexpected expense arises tomorrow. If your car breaks down and you have zero cash, you will simply put that repair back on the credit card. This creates a deeply frustrating cycle where you constantly pay off and rack up the exact same debt.
A common financial guideline suggests allocating a percentage of your bonus to build a starter emergency fund first. Establishing a cash buffer of at least $1,000 to $2,000 provides critical protection against minor life disasters. Once that safety net is fully funded, you can confidently hurl the rest of your bonus at your liabilities.
You can also employ a modified 50/30/20 rule to balance your financial goals with your psychological needs. Allocate 50% of the bonus to debt, 30% to emergency savings, and allow 20% for personal enjoyment. This balanced approach satisfies your psychological need for a reward while still making massive progress on your financial goals.
Allowing yourself a small reward prevents you from feeling entirely deprived of the fruits of your hard labor. When people feel overly restricted, they frequently rebel against their own budgets and engage in revenge spending. A modest dinner out or a small purchase keeps your morale high as you tackle the remaining balances.
Refinancing and Balance Transfer Opportunities to Pay Off Debt Faster
A typical work bonus might not be large enough to completely eliminate a massive, five-figure credit card balance. If you still have lingering high-interest debt after applying your windfall, look into strategic refinancing options to finish the job. You can use a balance transfer credit card to move the remaining debt to a 0% introductory APR offer.
Applying a bonus to lower the principal balance first makes it much easier to actually qualify for these promotional cards. Lenders look closely at your credit utilization ratio when deciding whether to approve your new credit application. By paying down a large chunk of debt with your bonus, you instantly boost your credit score and improve your approval odds.
Once you transfer the remaining balance to a 0% card, you buy yourself 12 to 18 months of interest-free breathing room. Divide the remaining balance by the number of promotional months to determine your new required monthly payment. This strategy allows you to aggressively pay off the debt without losing any more money to predatory interest charges.
If you can’t qualify for a balance transfer card, consider a fixed-rate personal consolidation loan instead. These loans may offer lower interest rates than your current credit cards. Consolidation can simplify your finances by combining multiple payments into one predictable monthly payment.
Avoid the Dangerous Lifestyle Creep Trap After Debt Elimination
Eliminating a monthly payment frees up highly valuable cash flow in your regular, everyday household budget. Many people make the critical mistake of immediately absorbing this new cash flow into their daily consumer spending habits. This phenomenon, widely known as lifestyle creep, prevents you from building actual wealth after getting out of debt.
You must actively redirect the money you previously spent on debt payments toward productive financial goals. Set up an automatic, recurring transfer from your checking account to your investment portfolio or high-yield savings account. If you never see the extra money sitting idle in your checking account, you will not be tempted to spend it.
Consider increasing your regular payroll contributions to your workplace retirement plan, such as a 401(k) or 403(b). If your employer offers a matching contribution, capturing that free money should be your absolute next major priority. Maximizing these tax-advantaged accounts allows your wealth to compound rapidly over the next several decades.
The ultimate goal of paying off debt is to shift your financial focus from surviving to thriving. You worked hard to earn that bonus, and applying it to your liabilities was a mature, strategic decision. Now, you must maintain that same level of discipline to make sure your net worth continues moving in a positive direction.
- Always establish a starter emergency fund before directing all your extra cash toward debt payoff.
- Use strategic balance transfers to eliminate interest charges on any debt remaining after your bonus is applied.
- Prevent lifestyle creep by automatically investing the monthly cash flow freed up by your paid-off debts.
Final Considerations for Managing Unexpected Wealth
Managing a sudden influx of cash requires significant discipline, foresight, and a clear understanding of your long-term financial priorities. Paying off debt might not feel as glamorous as booking a luxury vacation, but the resulting peace of mind is priceless. You are literally buying back your future income and drastically reducing the stress associated with heavy monthly obligations.
Take the time to properly celebrate your progress once you hit the submit button on those large debt payments. Recognizing your financial victories helps reinforce positive money management behaviors for the future. You are taking a massive, quantifiable step toward absolute financial independence and stability.
Keep monitoring your credit report as those balances drop to zero to verify that the creditors report the updates accurately. As your credit score naturally improves, you will qualify for better mortgage rates, cheaper auto insurance, and premium financial products. Use this incredible momentum to stay out of debt permanently and start building lasting generational wealth.