Debt consolidation often feels like a lifeline when multiple high-interest payments start overwhelming your monthly household budget. Combining several individual balances into a single, manageable debt consolidation loan can save you thousands of dollars over time. However, learning how to prepare for debt consolidation requires a clear-eyed assessment of your finances and strategic financial planning before you apply for new credit to manage your credit card debt.
Jumping into this financial strategy without proper groundwork often leads to significantly worse financial trouble down the road. This guide explains the exact steps required to organise your financial life before applying for new credit. We cover everything from tallying your current obligations to choosing the appropriate financial vehicle for your specific situation.
Total household debt in the United States reached $17.5 trillion in late 2023, according to the Federal Reserve Bank of New York. Credit card balances alone surpassed the $1 trillion mark during this specific reporting period. Before you can fix a financial problem, you must understand exactly how much it costs you each month.
Many borrowers focus only on their minimum monthly payments and ignore the massive interest charges accruing behind the scenes. You pay an average interest rate of over 22% on standard credit cards in the current market. If you carry a $10,000 balance, you lose hundreds of dollars to interest charges every single billing cycle.
Consolidating this debt makes mathematical sense if the new interest rate sits significantly lower than your current blended interest rate. You must calculate this blended interest rate across all your accounts to establish a baseline for comparison. Gather your most recent statements for every credit card, personal loan, and medical bill to find these numbers.
Write down the annual percentage rate for each specific account you want to include in your plan. This data forms the foundation of your entire repayment strategy moving forward. Without these numbers, you cannot accurately judge whether a new loan offer actually saves you real money.
Debt Consolidation Loan Strategy: Calculate Your Total Debt Burden
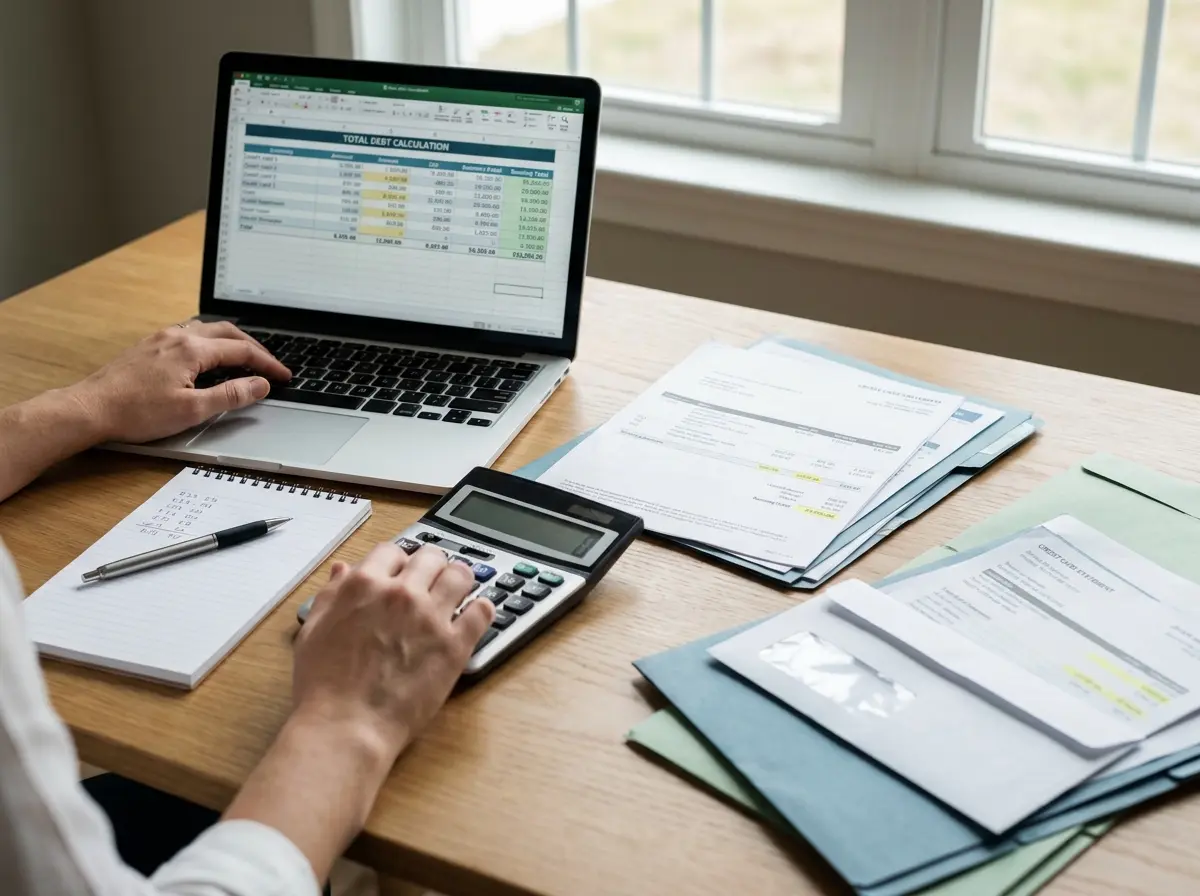
Getting a clear picture of your total obligations requires more than a glance at your banking app. You need a comprehensive inventory of every dollar you owe to external creditors and financial institutions. This inventory acts as your primary reference document throughout the entire formal application process.
Lenders will ask for exact payoff amounts, so you must have these figures readily available. Start by categorising your financial obligations into secured and unsecured debts. Debt consolidation primarily targets unsecured accounts like credit cards, outstanding medical bills, and high-interest payday loans.
Auto loans and mortgages typically do not belong in a standard consolidation plan. Focus your energy on the high-interest revolving credit lines that drain your monthly cash flow. You can use a simple spreadsheet or a physical notebook to track these specific details efficiently.
How to Calculate Your Exact Debt Load
List All Active Creditors
Gather every recent physical or digital statement and write down the name and contact information for each lender.
Record Exact Payoff Amounts
Log into your online banking portals to find the current real-time balance, rather than relying on last month’s statement.
Note Monthly Minimums
Document the lowest acceptable payment for each account to understand your current baseline cash flow requirements.
Improve Your Credit Score: Review Your Profile Thoroughly
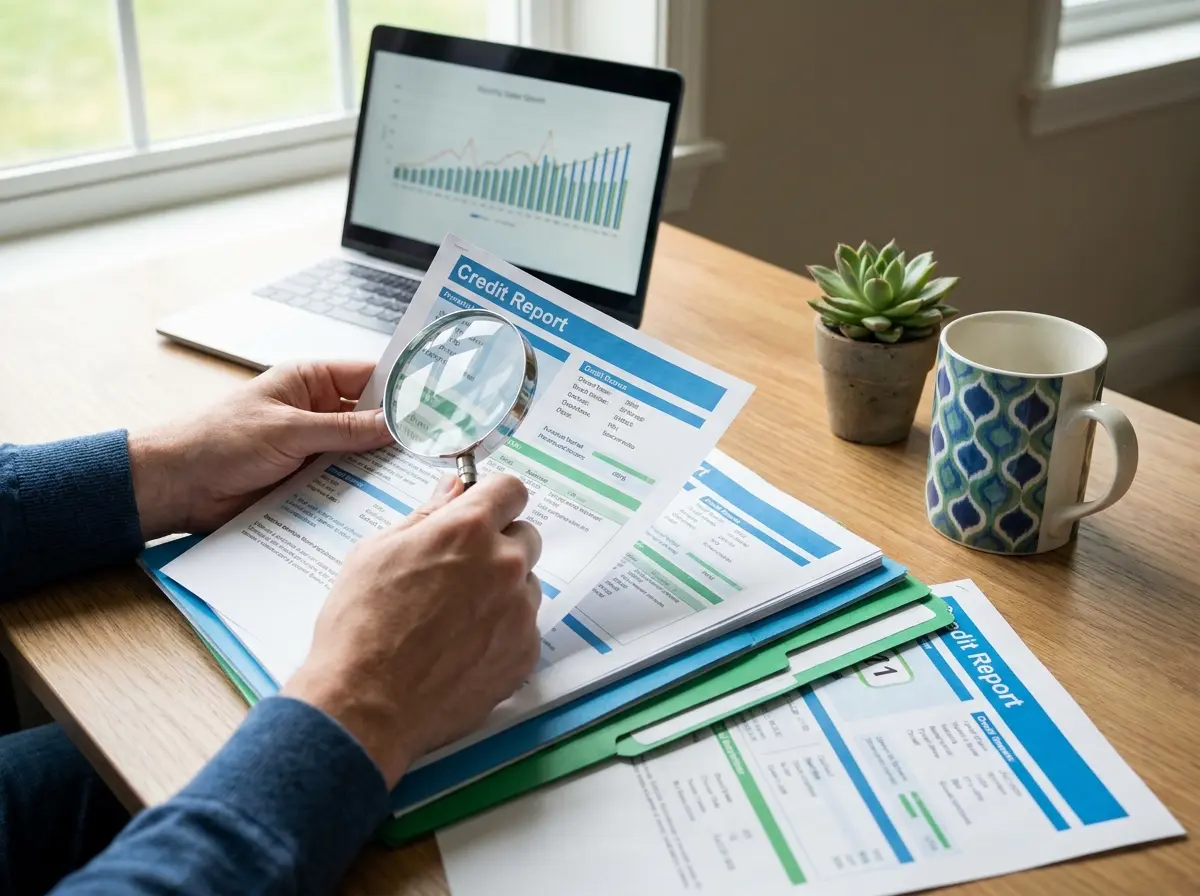
Lenders rely heavily on your credit history to determine your risk level and assign an interest rate. A strong credit profile opens doors to favorable terms, while a poor history limits your options significantly. You should pull your credit reports from all three major bureaus before submitting any formal applications.
The Fair Credit Reporting Act guarantees your right to one free report weekly via AnnualCreditReport.com. Scan these comprehensive reports for errors, duplicate accounts, or fraudulent activity that might drag down your score. The Federal Trade Commission notes that many consumers have verified errors on their credit reports.
Disputing these inaccuracies can rapidly improve your credit score before you apply for a new financial product. Give the bureaus at least thirty days to investigate and resolve any disputes you file formally. Pay close attention to your credit utilisation ratio, which measures how much available credit you currently use.
This single metric accounts for nearly a third of your total FICO credit score calculation. High balances on multiple cards signal extreme financial distress to potential lenders evaluating your application. Paying down small balances before applying for a new loan can yield a noticeable bump in your score.
- Review your credit reports from Equifax, Experian, and TransUnion to identify and dispute any costly errors.
- Lower your credit utilization ratio by paying off small balances before submitting formal loan applications.
- Calculate your exact total debt burden and blended interest rate to establish a baseline for comparison.
Stop Credit Card Use: Halt All New Borrowing to Prepare for Debt Consolidation
The most common reason these financial strategies fail is the borrower’s refusal to change their spending habits. Taking out a new loan to pay off credit cards frees up your available credit limits immediately. If you continue using those cards for everyday purchases, you will quickly double your total debt burden.
You must commit to a total freeze on new borrowing before you move forward with the process. Remove your saved credit card information from online retailers, digital wallets, and food delivery applications. Put your physical cards in a secure location where you cannot easily access them for impulse purchases.
Switch entirely to cash or a dedicated debit card for your daily living expenses and groceries. This physical friction helps break the psychological habit of relying on borrowed money to fund your lifestyle. Do you have the discipline to live strictly within your current monthly income limits?
If you cannot answer yes to that question, a new loan will likely worsen your financial situation. You must address the root cause of your overspending before treating the symptom with a new product. Take a few weeks to practice living without credit before signing any binding legal agreements.
Do not close your old credit card accounts immediately after paying them off with a consolidation loan. Closing old accounts reduces your average credit age and lowers your overall available credit, which damages your score.
Debt Management Planning: Build a Bare-Bones Budget
A successful strategy relies entirely on your ability to make the new payment on time every month. You need absolute certainty that your monthly income covers your living expenses and this new debt obligation. Creating a bare-bones budget reveals exactly how much free cash flow you can dedicate to debt repayment.
This demanding exercise strips away luxury spending to show your true financial capacity and limitations. Track your actual spending for the last sixty days using bank statements and credit card transaction logs. Categorise every transaction into essential needs, such as housing, and discretionary wants, like dining out.
Be brutally honest with yourself about where your money actually goes each month. Many people discover hundreds of dollars in forgotten subscription services or impulse purchases during this thorough review. Cancel any recurring charges that do not directly support your basic living requirements or debt payoff goals.
Calculate the maximum monthly loan payment your newly trimmed budget can comfortably support without causing stress. Do not commit to a monthly payment that leaves you with zero margin for financial error. Unexpected expenses will inevitably arise, and you need a small cash buffer to avoid relying on credit.
Compare Personal Debt Consolidation Loans and Other Methods
Consumers have several different avenues available for combining their high-interest debts into a single payment. The right choice depends heavily on your credit score, total debt amount, and current homeownership status. You must evaluate the pros and cons of each method to find the most cost-effective solution.
Let us examine the primary vehicles for restructuring your obligations in the current financial market. Taking out debt consolidation loans represents just one of several paths you can take to streamline your payments. Each option carries specific qualification requirements and potential risks that you must carefully consider.
Balance Transfer Credit Cards
Balance transfer credit cards offer a temporary zero-percent interest period for qualified applicants. This promotional window typically lasts between twelve and twenty-one months, depending on the specific card issuer. This option works beautifully if you can aggressively pay off the entire balance before the promotion expires.
However, these credit cards usually charge an upfront transfer fee of three to five percent. You also need an excellent credit score to qualify for a limit high enough to cover everything. If you fail to clear the balance in time, the remaining amount reverts to a high interest rate.
Personal Consolidation Loans
Personal loans provide a fixed interest rate and a predictable monthly payment over a set term. These unsecured loans range from two to seven years, giving you a clear timeline for becoming debt-free. Lenders often send the funds directly to your creditors, which simplifies the entire payoff process immensely.
Interest rates vary widely based on your creditworthiness and current debt-to-income ratio. You should pre-qualify with multiple lenders to compare offers and find the lowest possible annual percentage rate. Fixed payments make budgeting much easier than dealing with fluctuating credit card minimums.
Home Equity Options
Homeowners might consider tapping into their home equity through a specialized loan or line of credit. Secured loans generally offer the lowest interest rates available on the consumer financial market. Lenders feel confident offering better terms because your property backs the borrowed amount.
However, you put your primary residence at risk of foreclosure if you default on the monthly payments. You should exhaust all unsecured options before putting your home on the line to pay off credit cards. This strategy requires careful consideration and a rock-solid commitment to making every payment on time.
Many online lenders allow you to check your estimated interest rate using a soft credit pull. Take advantage of these pre-qualification tools to compare multiple offers without damaging your official credit score.
Loan Application Prep: Gather Your Financial Documentation
Lenders require concrete proof of your financial stability before approving a substantial loan application. Gathering this essential paperwork in advance speeds up the timeline and prevents frustrating administrative delays. You should create a secure digital folder on your computer to store these documents safely.
Having everything organized demonstrates high financial responsibility to prospective lenders reviewing your file. Start by collecting your two most recent pay stubs to verify your current employment and income level. Self-employed individuals will need to provide two years of personal and business tax returns instead.
Lenders use this verified income information to calculate your official debt-to-income ratio accurately. This critical metric heavily influences their underwriting process and final approval decisions. A ratio above forty percent often triggers automatic rejections from traditional financial institutions and credit unions.
You also need exact payoff letters from your current creditors if the new lender pays them directly. These formal letters specify the exact amount required to close the account on a specific date. Keep in mind that interest accrues daily, so request these letters right before you submit your personal loan application.
- Compare multiple financial products to find the lowest interest rate and most favorable repayment terms.
- Gather your pay stubs, tax returns, and exact payoff letters before starting the formal application process.
- Utilize soft credit checks to pre-qualify for personal loans without impacting your official FICO score.
Prepare for the Best Debt Consolidation Loan Application Process
Once you have selected a lender and gathered your documents, you are ready to begin the formal application. Most modern lenders offer a streamlined digital application that takes less than fifteen minutes to complete. Ensure you have a stable internet connection and access to your digital financial records before starting.
Be prepared to explain the purpose of the loan, which in this case is debt consolidation. Some lenders may offer a lower interest rate if you agree to let them pay your creditors directly. This feature ensures the funds are used as intended and can sometimes simplify the approval process.
Double-check all the information you enter for accuracy, as small typos can lead to automatic denials or delays. After submission, the lender may request additional clarification or updated documents. Respond to these requests promptly to keep your application moving through the underwriting pipeline.
Financial Stability Tips: Establish Post-Consolidation Habits
The final step in learning how to prepare for debt consolidation is planning for life after the loan is funded. Success is not defined by getting the loan, but by successfully paying it off and remaining debt-free. You must maintain the disciplined spending habits you developed during the preparation phase.
Set up automatic payments for your new consolidation loan to ensure you never miss a due date. Missing a single payment can severely damage your credit score and trigger expensive late fees. Consider building an emergency fund alongside your loan payments to cover unexpected costs without using credit.
Regularly review your budget to ensure you are staying on track with your financial goals. If you find yourself tempted to use your credit cards again, remind yourself of the progress you have made. True financial freedom comes from consistent habits and a long-term commitment to living within your means.
Conclusion
Preparing for debt consolidation is a comprehensive process that requires patience, organization, and a shift in mindset. By understanding your true costs, reviewing your credit, and comparing your options, you position yourself for a successful transition. Remember that the loan is a tool, and your daily financial choices are what will ultimately lead to lasting stability.
Take control of your monthly payments and reduce financial stress. Find out if debt consolidation is right for you with Lendwyse.