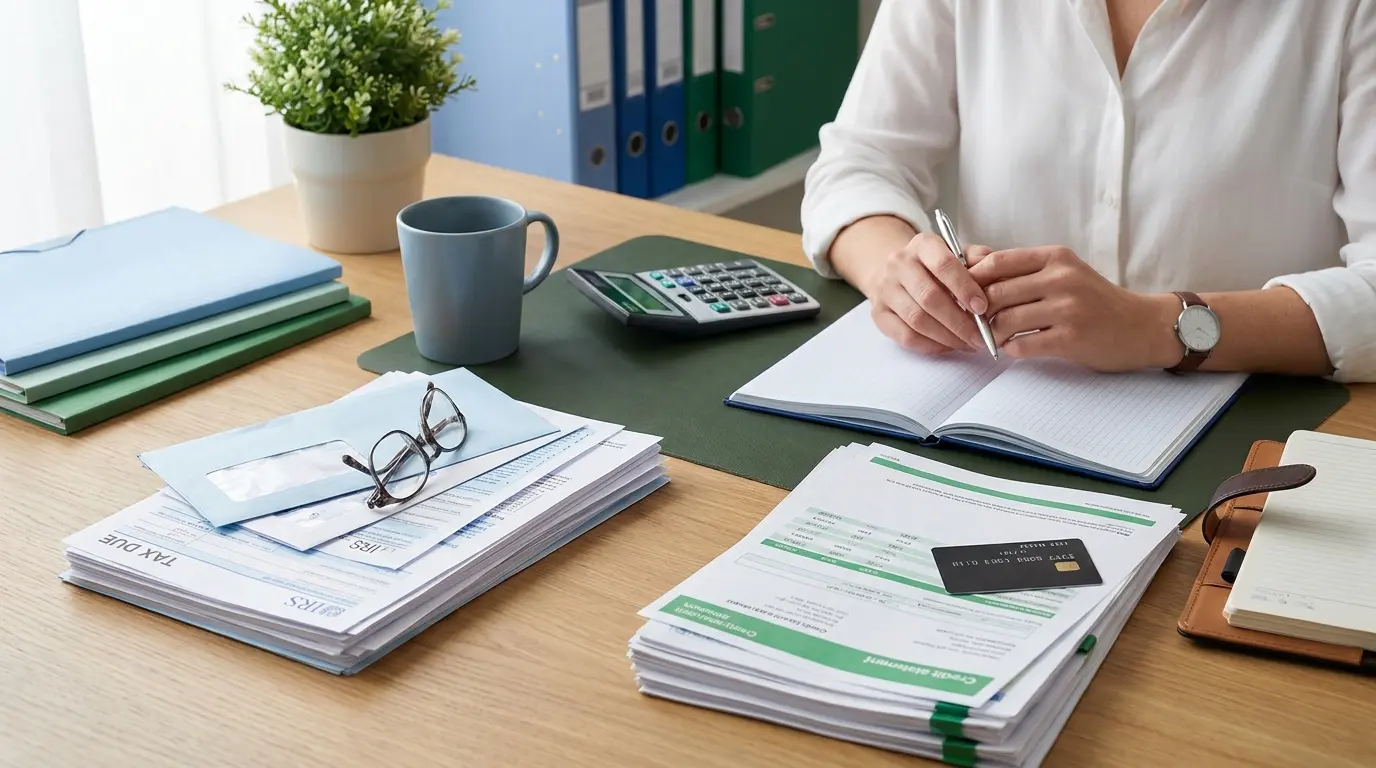
Facing a mountain of bills is stressful, especially when determining what to do when you have tax debt and credit card debt simultaneously. This pressure multiplies rapidly if you owe money to both credit card issuers and the Internal Revenue Service. Understanding the specific rules governing these obligations is the essential first step toward achieving total financial recovery.
The government holds immense power to collect what you owe them through administrative actions. Credit card companies can certainly damage your financial health, but their collection methods take much longer to execute. Understanding these differences helps you allocate limited funds efficiently while protecting assets from a potential tax lien. This guide breaks down exactly how to handle both masters without losing your financial footing.
Holding both types of debt simultaneously creates a dangerous financial squeeze that requires immediate attention. Credit cards carry notoriously high interest rates that compound daily, making them difficult to pay off. These balances can double in just a few years if you only make minimum payments, draining your disposable income.
Tax debt operates differently but carries far more severe enforcement actions than standard consumer loans. The IRS charges interest and penalties, though usually at a lower combined rate than a standard credit card. However, the federal government does not need a court order to seize your property or garnish your wages.
Balancing these two financial burdens requires clear-headed decision-making and a commitment to a long-term tax debt relief strategy. Many people panic and throw all their spare cash at credit cards because collectors call them relentlessly. Ignoring federal notices represents the biggest mistake you can make, as the IRS relies heavily on automated enforcement.
- The IRS possesses immediate collection powers that credit card companies lack.
- Credit cards grow faster due to high compound interest rates.
- Ignoring IRS letters will eventually lead to wage garnishment or bank levies.
Prioritizing Payments: IRS Tax Debt and Credit Card Debt Relief
You must establish a strict hierarchy for your payments to avoid severe legal consequences. The federal government always stands at the front of the line when it comes to debt collection. If you have limited funds, securing a formal tax debt relief agreement with the IRS takes absolute precedence.
The Consequences: IRS Tax Debt and Collection Actions
The IRS can file a Notice of Federal Tax Lien against you to protect its interests. This public document alerts creditors that the government has a legal right to your property, making it difficult to sell assets. Furthermore, they can issue a wage garnishment to your employer, forcing them to send your paycheck directly to the Treasury.
Credit card companies must jump through multiple legal hoops to achieve the same result in civil court. They must sue you, win a judgment, and then apply for a garnishment order, which takes significant time. The IRS skips all these steps because federal law grants it administrative collection powers that other creditors simply do not have.
Therefore, your primary goal is to stop IRS enforcement actions immediately through formal communication. You achieve this by setting up a formal resolution or an IRS installment agreement to manage the balance. Once you establish a payment plan or hardship status, the IRS generally halts all aggressive collection efforts against you.
The IRS charges a Failure to Pay penalty of 0.5% per month, plus fluctuating interest. If you also failed to file your return, they add a massive 5% per month Failure to File penalty.
Managing Minimum Payments on Credit Card Debt
While you focus on the IRS, do not completely abandon your credit cards if you can avoid it. Missing credit card payments destroys your credit score very quickly, which limits your future financial options for housing or transportation. A low credit score can make it nearly impossible to qualify for better interest rates later.
Your strategy should be to pay the absolute minimum on all credit cards to keep them current. Channel every remaining dollar toward resolving your tax situation to prevent the government from taking more drastic measures. This prevents charge-offs and maintains your credit history while you neutralize the biggest threat to your financial livelihood.
If you genuinely cannot afford both, you must prioritize the tax agreement over consumer debt. Defaulting on unsecured consumer debt is terrible, but losing your paycheck to a federal levy is devastating. You can rebuild your credit later, but you cannot easily reverse an active IRS garnishment once it begins.
Tax Debt Relief: Proven Strategies and Options for the IRS
The IRS offers several formal programs to help taxpayers resolve their balances in a manageable way. They actually want to work with you, provided you remain communicative and proactive throughout the entire process. You should explore tax debt relief options to see which specific program fits your current financial reality.
Setting Up an IRS Installment Agreement for Relief
An IRS installment agreement allows you to pay your balance over a set period, usually up to 72 months. If you owe less than $50,000, you can typically apply for a streamlined agreement online without much hassle. The IRS rarely asks for detailed financial statements if you meet these criteria and agree to direct debit payments.
The monthly payment usually equals your total balance divided by 72 to ensure the debt is cleared. For example, if you owe $10,000, your payment would be roughly $139 per month plus interest. Penalties continue to accrue, but the Failure to Pay penalty drops from 0.5% to 0.25% per month while the agreement remains active.
You must stay compliant with all future tax filings to keep the agreement in good standing. If you miss a payment or incur new tax debt the following year, the IRS will default your agreement. Reinstating a defaulted agreement costs additional fees and subjects you to much stricter scrutiny from the agency.
Settling Debt: Submitting an Offer in Compromise (OIC)
An Offer in Compromise allows you to settle your tax debt for less than the full amount owed. The IRS accepts an OIC if they determine they cannot reasonably collect the full balance before the collection statute expires. This is a rigorous, mathematically driven process that requires full financial disclosure.
The IRS calculates your Reasonable Collection Potential (RCP) by looking at your asset equity and future income. They look at your asset equity and your past and future income minus allowable living expenses. If your RCP is lower than your total tax bill, they might accept your settlement offer as a final resolution.
Be highly skeptical of companies promising pennies on the dollar settlements without reviewing your specific case. The official IRS data shows they accept fewer than a third of all submitted OICs. You must truly demonstrate severe financial hardship to qualify for this specific program.
Financial Hardship: Requesting Currently Not Collectible (CNC) Status
If you cannot afford any monthly payment, you can request the Currently Not Collectible status to stop collections. This program temporarily halts all IRS collection actions while you work to improve your financial situation. You must prove that paying the IRS would prevent you from meeting basic living expenses like housing and food.
The debt does not disappear under CNC status, and interest continues to grow on your account. Penalties and interest continue to grow on your account every single day until the balance is paid. The IRS will review your income annually to see if your financial situation has improved enough to start making payments.
This status provides vital breathing room for those facing extreme financial distress. It allows you to redirect your limited funds toward keeping the lights on and feeding your family. Once your situation stabilizes, you can transition into a standard installment agreement to pay off the remaining balance.
How to Apply for an IRS Installment Agreement
File All Past-Due Returns
The IRS requires you to be completely compliant before they approve any payment plan. You must submit all missing tax returns from previous years.
Calculate Your Monthly Payment
Divide your total tax debt by 72 to find your minimum required monthly payment. Make sure this amount fits comfortably within your household budget.
Submit Form 9465 or Apply Online
Log in to your IRS.gov account to use the Online Payment Agreement tool. Alternatively, you can mail Form 9465 to request your installment plan manually.
Effective Solutions: Tackling High-Interest Credit Card Debt Relief
Once you secure your IRS situation, you can aggressively attack your credit card balances to save on interest. Consumer debt requires a methodical approach to minimize the interest you pay over time and clear the debt. You need a structured plan rather than randomly throwing extra cash at different accounts each month.
The Debt Avalanche Method for Credit Card Debt Relief
The debt avalanche method saves you the most money mathematically by targeting high-interest rates. You list all your credit cards from the highest interest rate to the lowest to prioritize payments. You continue paying the minimum on every card, but you push every extra available dollar toward the card with the highest APR.
Once that first card reaches a zero balance, you take the money you were paying on it and apply it to the next card. This creates an avalanche effect that accelerates your progress toward becoming debt-free. You eliminate the most expensive debt first, which stops compounding interest from draining your wallet every month.
Some people prefer the debt snowball method, where they pay off the smallest balance first for a psychological win. While the snowball method feels good early on, the avalanche method keeps more cash in your bank account over the long run. When dealing with the stress of dual debt, mathematical efficiency matters most for your recovery.
Strategic Debt Consolidation and Balance Transfers
If your credit score remains relatively healthy, you might qualify for a 0% introductory APR balance transfer card. You can move your existing high-interest balances to this new card to save on interest costs. This pauses the interest accumulation for 12 to 21 months, allowing your payments to hit the principal directly.
You must factor in the balance transfer fee, which usually ranges from 3% to 5% of the total amount moved. Make sure you can pay off the entire balance before the promotional period expires to avoid new interest. If you leave a balance after the promo ends, the interest rate will skyrocket back to normal levels.
Alternatively, a personal credit card consolidation loan provides a fixed interest rate and a structured payoff timeline for your debt. You borrow enough to pay off all your credit cards at once and simplify your monthly bills. You then make one predictable monthly payment to the loan provider at a lower rate than the credit cards charge.
After paying off a credit card, leave the account open. Closing the account reduces your total available credit, which increases your credit utilization ratio and damages your credit score.
Professional Help: Working with Credit Counseling Agencies
If you cannot qualify for new credit, consider contacting a non-profit credit counseling agency for professional help. Organizations approved by the Department of Justice can help you set up a debt management plan (DMP). The counselor acts as an intermediary between you and the credit card companies to lower rates.
Under a DMP, the agency negotiates lower interest rates and waives late fees on your behalf to make payments manageable. You make one lump-sum payment to the agency each month, and they distribute the funds to your creditors. These plans typically take three to five years to complete and require strict adherence.
Be aware that participating in a DMP requires you to close your credit card accounts to prevent new debt. This will temporarily lower your credit score due to the reduction in available credit. However, establishing a consistent payment history and eventually eliminating the debt will improve your financial profile dramatically over time.
Financial Analysis: Can You Use Credit Cards to Pay Tax Debt?
People often wonder if they should just pay their IRS balance with a credit card to simplify things. The IRS accepts credit card payments through authorized third-party processors who handle the transactions. These processors charge a convenience fee, currently hovering around 1.85% to 1.98% of the transaction amount.
You must run the numbers carefully before choosing this path to ensure it makes financial sense. If you put a $5,000 tax bill on a credit card charging 24% APR, you are making a terrible financial mistake. The IRS interest rate and penalties are significantly lower than standard credit card rates for most taxpayers.
However, this strategy makes sense in one specific scenario involving promotional credit offers. If you qualify for a new credit card with a 0% introductory APR, you can pay the tax bill with that card. This credit card consolidation tactic completely removes the IRS from your life immediately while giving you time to pay.
- Use the debt avalanche method to target high-interest credit cards mathematically.
- Balance transfers only work if you can pay the debt before the promo period ends.
- Never pay the IRS with a standard high-interest credit card.
Bankruptcy: The Last Resort for Tax and Credit Card Debt Relief
When the math simply does not work, and you cannot cover your basic living expenses, bankruptcy becomes a viable option. Filing for bankruptcy stops all collection actions immediately through an automatic stay provided by the court. It forces creditors, including the IRS, to halt garnishments and phone calls while the court reviews your case.
Chapter 7 bankruptcy liquidates your non-exempt assets to pay creditors and discharges the remaining unsecured debt. Credit card balances easily disappear in a Chapter 7 filing, providing a fresh start for many debtors. Chapter 13 bankruptcy reorganizes your debt into a court-mandated repayment plan lasting three to five years based on income.
Discharging tax debt through bankruptcy involves highly specific rules that must be followed exactly. Income tax debt can be discharged if it meets several strict timeframes regarding filing and assessment. The tax return must have been due at least three years before filing and assessed at least 240 days prior.
Only income taxes can be discharged in bankruptcy. Payroll taxes, fraud penalties, and unfiled tax years will survive the bankruptcy process and remain your responsibility.
You should consult a qualified bankruptcy attorney before making this decision to ensure you qualify. They will review your entire financial picture and determine if filing makes sense for your specific situation. Bankruptcy stays on your credit report for up to ten years, so treat it as an absolute last resort.
Long-Term Recovery: Building a Sustainable Financial Plan
Solving your current debt crisis only represents half the battle in achieving long-term financial health. You must fix the underlying issues that caused the balances to grow in the first place to avoid recurrence. Without fundamental changes to your financial habits, you will end up back in the same situation next year.
Start by addressing the tax problem at its source through proper withholding or estimated payments. If you owed the IRS because of insufficient withholding, update your Form W-4 with your employer immediately. Having a little extra withheld from each paycheck hurts less than facing a massive surprise bill in April.
Next, you must build a starter emergency fund of at least $1,000 to cover unexpected costs. People rely on credit cards because they lack cash reserves for unexpected expenses like car repairs or medical bills. Having a small cash buffer breaks the cycle of relying on high-interest plastic to survive everyday emergencies.
Finally, track your income and expenses meticulously to ensure you are living within your means. Every dollar you earn needs a specific job to help you reach your financial goals. Consistency and discipline will ultimately pull you out of the financial hole and toward a more stable future.
Conclusion
Dealing with tax debt and credit card balances simultaneously requires a clear, prioritized approach to succeed. The IRS holds the power to disrupt your life through levies and garnishments, so you must address them first. Establish an IRS installment agreement or hardship status to protect your assets and your income immediately.
Once the federal government is satisfied, turn your full attention to the credit cards for credit card debt relief. Utilize the debt avalanche method or balance transfer strategies to eliminate the high-interest balances systematically. Start by listing every single debt you owe today, and take that first step toward financial freedom.