Struggling with multiple bills and high interest rates can keep you stuck in a cycle of minimum payments. Many people face this challenge in today’s unpredictable economy. Peer-to-peer lending offers a way to consolidate debt into one fixed, manageable loan.
This approach lets you borrow directly from individual investors instead of traditional banks. It can lead to more competitive terms and simplify your monthly payments. With one loan, you can focus more on long-term financial stability rather than juggling multiple debts.
Understanding how peer-to-peer lending works helps you make smarter financial decisions. It also shows how to protect your credit and navigate these platforms effectively. With the right strategy, you can regain control and move toward a stronger financial future.
A peer-to-peer loan connects borrowers directly with individual investors through a sophisticated online marketplace that handles all the logistics. You do not borrow money from a bank or a credit union in the conventional sense that most people are used to. Instead, everyday people fund your personal loans in small increments, creating a decentralized funding model that benefits everyone involved. This system is often referred to as peer-to-peer lending, and it has grown significantly since its inception in the mid-2000s. Borrowers use these funds for various reasons, including debt consolidation, home improvement projects, or even starting a small business. The investors provide the capital because they want to earn higher returns than standard savings accounts offer at a financial institution.
This setup benefits both sides of the financial transaction significantly by cutting out the overhead costs associated with physical bank branches. If you have a solid credit history and a healthy credit score, you might qualify for a lower annual percentage rate than credit card companies charge. You apply for a personal loan through a lending platform, which acts as the intermediary and regulatory watchdog for the process. The platform assesses your credit score and assigns you a specific risk grade based on your historical financial behavior. Investors review these grades before deciding where to put their money, allowing them to build a diversified portfolio of personal loans across different risk levels. This transparency ensures that both the borrower and the lender understand the terms of the agreement before any money changes hands.
Many people use peer-to-peer lending to pay off high-interest debt rapidly and efficiently without the hassle of traditional underwriting. You can take out one large personal loan to clear multiple balances entirely, including high-interest credit card debt that may be dragging you down. This leaves you with a single monthly payment to manage moving forward, which reduces mental clutter and financial anxiety. A single fixed rate makes household budgeting much simpler than tracking various fluctuating rates across multiple accounts. You also avoid dealing with multiple due dates and potential late fees across different accounts, which can further damage your credit profile if missed. By consolidating, you are essentially trading several high-interest headaches for one predictable and manageable monthly obligation.
The Mechanics of a Peer-to-Peer Lending Platform and Investor Relations
Every lending platform operates as a digital matchmaker between borrowers and investors, utilizing advanced algorithms to pair them effectively. You submit a loan application outlining exactly how much capital you need and why you need it for your consolidation efforts. The platform then verifies your identity and reviews your financial background thoroughly to ensure security and prevent fraudulent activity. They check your credit score and employment status to verify your ability to repay the peer-to-peer loan over the agreed-upon timeframe. This evaluation ultimately determines the interest rate you will pay, with lower-risk borrowers receiving the most favorable rates available on the market.
Once approved, your request goes live on the digital marketplace for potential investors to see and evaluate based on their goals. Individual investors browse these listings and choose which personal loans to fund based on their personal risk tolerance and desired return. An investor might contribute as little as twenty-five dollars to your request to diversify their portfolio across many different borrowers. Hundreds of different people might fund a single personal loan, spreading the risk among the group while providing you with the full amount. Once the total requested amount is reached, the platform transfers the money directly to your bank account, often within a few business days. This speed is one of the primary advantages of using a modern fintech platform over a slow-moving traditional lender.

You then make regular loan payments directly to the online platform rather than to the individual investors who funded your request. The platform automatically distributes the principal and interest back to the participating investors after taking a small service fee for their efforts. This system requires a clear privacy policy to protect everyone involved in the transaction and ensure data security across the board. Borrowers remain completely anonymous to the investors funding their requests, protecting your personal information and financial privacy. You never have to interact directly with the people financing your peer-to-peer lending request, as the platform handles all communication and payment processing. This professional separation ensures that the lending process remains objective and strictly focused on the financial terms agreed upon.
- Peer marketplaces connect you directly with individual investors rather than traditional banks.
- Your assigned risk grade and credit score determine the interest rate you will pay.
- Multiple investors can fund a single personal loan request in small increments.
How Peer to Peer Lending Works for Debt Consolidation: The Step-by-Step Guide
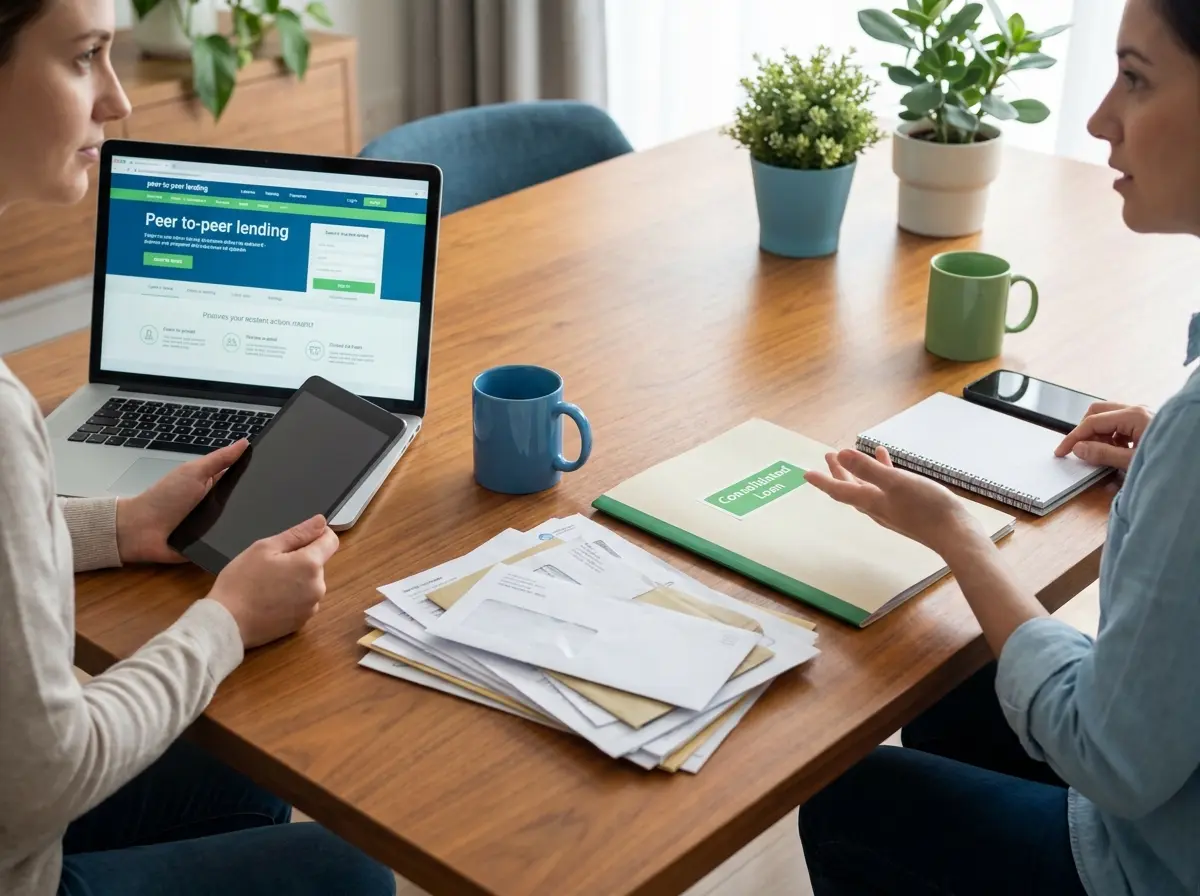
Let us break down the exact steps to organize your finances using this modern and efficient method. The process is straightforward if you gather your information beforehand and understand the specific requirements of the platform. Having your financial documents ready speeds up the approval timeline and reduces stress during the application phase of the journey. Most platforms will require proof of income, such as recent pay stubs or tax returns, to verify your ability to handle the new payment.
How to Start the Consolidation Process
Calculate Your Total Debt
Add up every outstanding credit card balance you want to clear. This gives you the exact loan amounts you need to request from the platform to be successful.
Check Your Credit Profile
Platforms use your credit profile to set your percentage rate. Review your reports for any errors before applying to ensure you get the best loan terms possible.
Compare Marketplaces
Look at different peer-to-peer lending platforms, such as Lending Club, to find the best terms. Some cater specifically to borrowers with different credit backgrounds and needs.
Apply and Pay Creditors
Fill out the application and wait for investors to fund your request. Once funded, use the money to pay off your credit card creditors immediately to stop interest.
Paying off creditors quickly stops high interest from growing and saves money over time. Avoid using cleared credit cards again, as this defeats the purpose of consolidation. Keeping accounts open but unused can help your credit utilization, and some platforms can pay creditors directly for convenience.
This strategy requires strong discipline to be effective long-term. Adding new debt while repaying a loan can worsen your financial situation. You could end up with double the debt and a much tighter budget.
To stay on track, limit access to your credit cards during repayment. Focus on changing spending habits and building better financial discipline. Long-term success depends on consistency and commitment.
Evaluating the Total Cost of Your Peer-to-Peer Loan and Loan Terms
When borrowing, look beyond the interest rate and consider all fees. Many platforms charge an origination fee, often deducted before you receive the funds. This means you may need to request more than your exact debt amount to cover everything.
Always calculate the total cost of the loan before committing. Compare it with your current debts to ensure the new rate and fees actually save you money. The benefit should clearly outweigh the costs.
Also consider the loan term, as it affects both monthly payments and total interest. Longer terms lower monthly bills but increase overall costs. Choose a balance that fits your budget while minimizing long-term expenses.
Always factor origination fees and loan terms into your requested amount. If a platform charges a five percent fee on a $10,000 personal loan, you will only receive $9,500 in your savings account, which might not cover all your credit card balances. This discrepancy can leave you with lingering high-interest debt if you are not careful with your initial calculations.
Some platforms penalize you for paying off your balance early, though many modern P2P lenders do not follow this practice. You should read the fine print regarding prepayment penalties before accepting any funds from a financial institution or peer group. The best personal loans allow you to pay extra toward the principal whenever you have extra cash without any extra charges.
This flexibility can help you become debt-free even faster than the original schedule suggests, saving you even more on interest. Understanding these nuances is a key part of how peer-to-peer lending works for debt consolidation successfully and sustainably.
Small Business Debt, Business Loans, and Peer Lending Opportunities
Peer-to-peer lending isn’t just for individuals—it can also support entrepreneurs. Many business owners use it to avoid slow bank processes and reduce high-interest startup debt. Consolidating into one loan can improve cash flow and free up funds for growth.
For business loans, lenders may review factors beyond personal credit. They often consider revenue, industry, and whether you have business insurance. These details can make you a more attractive and lower-risk borrower.
These platforms offer flexibility for freelancers and small businesses alike. Faster funding is a major advantage when opportunities arise. This makes them a practical alternative to traditional bank financing.
Alternatives: Traditional Banks, Financial Institutions, and Credit Cards
Peer-to-peer lending is useful, but it’s not your only option for debt relief. Compare offers from banks, financial institutions, and credit unions to find the best rates. Checking multiple options helps you secure the most competitive terms.
A credit card with a 0% introductory APR on balance transfers can also be effective. It works well if you can pay off the balance within the promo period, usually 12–18 months. However, missing that window can lead to high interest rates.
For larger debts, personal loans often provide more stability. Fixed payments and a clear end date make repayment easier to manage. This structure helps you stay on track toward becoming debt-free.
Managing the Platform Interface, Credit Scores, and Main Menu
Once you choose a platform like Lending Club, you’ll use its interface to manage your loan. Most platforms are user-friendly, showing your balance, payment schedule, and progress. Setting up automatic payments helps you stay on track and maintain a strong payment history.
These platforms also let you monitor key details that affect your credit profile. Consistent payments improve your standing across major credit bureaus. Staying organized through the dashboard reduces the risk of missed deadlines.
Many platforms offer educational tools to improve financial literacy. You may find calculators and resources to help speed up debt repayment. Using these features can strengthen your habits and support long-term financial stability.
The Evolution of Marketplaces, Bad Credit Options, and Student Loans
The world of peer-to-peer lending is constantly evolving to meet new consumer needs and technological advancements. While it started primarily for credit card consolidation, it has expanded into many other areas of personal and professional finance. Some people now use these platforms to manage a student loan or multiple student loans with high interest rates that are difficult to pay. Consolidating student loans through a peer marketplace can sometimes offer a lower rate than private lenders, though you must be careful. Even individuals struggling with bad credit may find specialized investors willing to take a chance on their recovery if they show a steady income.
As these marketplaces mature, they are becoming more integrated with traditional banks and other financial institutions through partnerships. Some banks now fund personal loans directly through these platforms, combining tech efficiency with massive institutional capital. This evolution means more liquidity and potentially better rates for the average borrower who is looking for a fair deal. Whether you are looking for personal loans, business loans, or help with a student loan, the peer-to-peer model is here to stay. It represents a fundamental shift in how we think about borrowing and lending in the 21st century, putting power back in the hands of the people.
In conclusion, how peer-to-peer lending works for debt consolidation is a process of connecting with real people to solve complex financial problems. By bypassing the traditional bank, you can often find better rates and a more transparent experience than you would elsewhere. Remember to protect your credit score, compare loan terms, and stay disciplined with your spending throughout the entire process. With the right personal loan and a solid plan, you can break the cycle of debt and build a more secure financial future for yourself and your family. The journey to financial freedom starts with a single step, and for many, that step is a peer-to-peer consolidation loan.