Experiencing an unexpected job loss immediately creates significant financial stress and deep uncertainty for your entire household. Understanding how to handle debt after losing your job is a critical first step because this sudden change in your employment status forces you to reevaluate your budget and make difficult choices regarding existing bills. Addressing your financial obligations quickly prevents compounding late fees and protects your long-term economic stability. This period of transition requires a calm, analytical approach to ensure that temporary cash flow issues do not evolve into permanent credit damage.
The psychological impact of sudden unemployment often leads to a state of paralysis, where individuals avoid looking at their bank statements or opening mail from creditors. However, the most effective way to regain a sense of control is to confront the numbers directly and develop a comprehensive survival strategy. By treating your financial recovery as your new full-time job, you can navigate the complexities of debt management with professional precision. This guide provides the necessary framework to protect your assets while you search for your next career opportunity.
Before creating a recovery plan, understand your full financial situation. Check your primary and secondary accounts to see your available cash and review any automatic payments or subscriptions. This gives you a clear picture of your immediate spending power.
Next, assess your total liquid funds, including any emergency savings. Confirm the status of your final paycheck or severance and when you’ll receive them. Knowing these timelines helps you plan your cash flow for the coming weeks.
Consider selling non-essential items or seeking assistance programs to boost short-term funds. This ensures you’ve explored all options before using long-term savings. With a complete financial picture, you can build a realistic budget, avoid overdrafts, and manage obligations with more confidence.
How to Evaluate Your Finances
Calculate Available Funds
Review your primary bank account and savings balances to find your total cash on hand.
List All Debts
Write down every outstanding credit card, existing car loan, and personal financial obligation.
Review Monthly Expenses
Track your regular household spending to identify specific areas where you can save money immediately.
Prioritize Essential Expenses Over Debt Following Job Loss
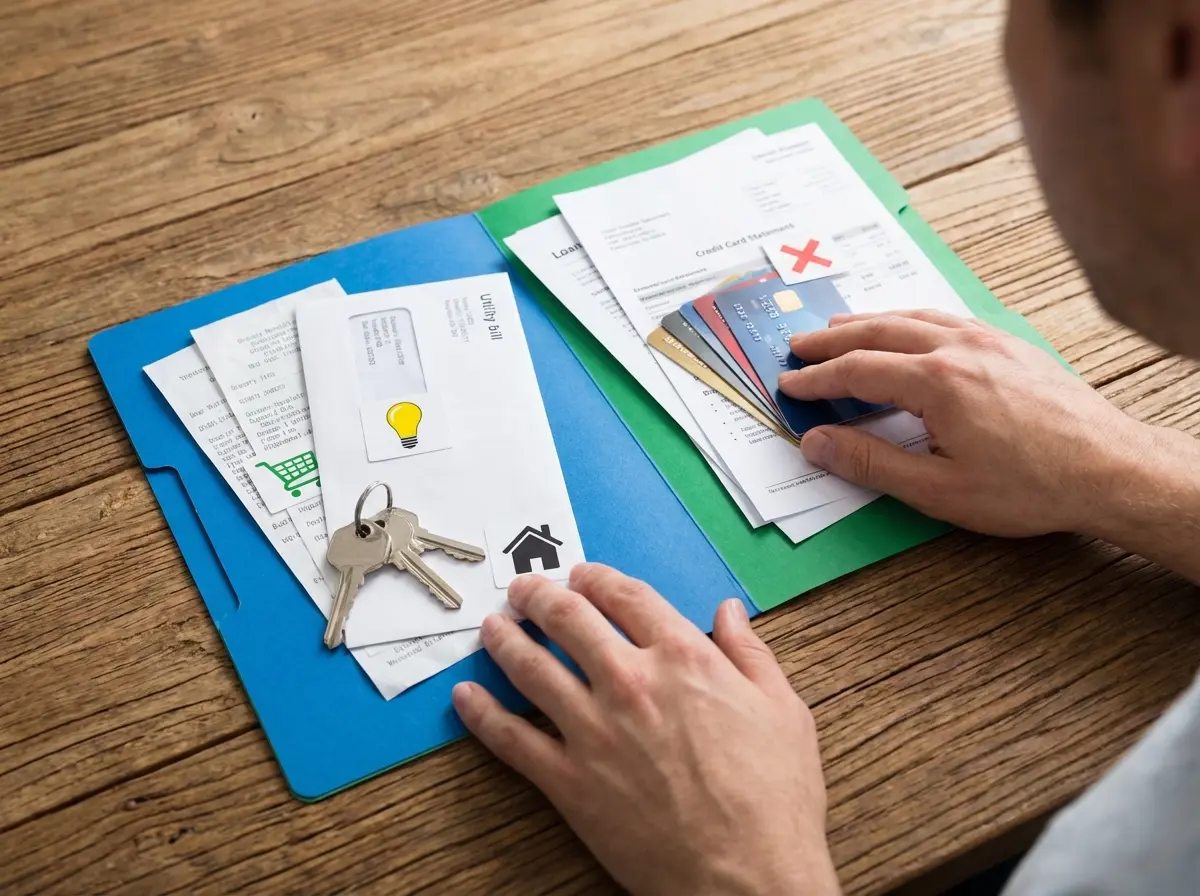
When you lose your steady income, you cannot continue paying every single bill at your previous level. You must prioritize basic living expenses like housing, utilities, food, and necessary transportation above all other financial obligations. Securing these basic human needs provides a stable foundation while you actively search for new employment opportunities. This “triage” approach ensures that you remain housed and healthy while you work through the logistics of debt repayment.
Maintaining your health insurance coverage should also rank exceptionally high on your list of critical priorities. A sudden medical emergency without adequate health insurance can easily create massive new financial burdens for your family. You might need to explore alternative options like COBRA coverage or state-sponsored health plans to bridge the coverage gap. Additionally, be aware of the No Surprises Act, which protects you from unexpected medical bills from out-of-network providers during emergencies.
Financial experts often refer to these priorities as the “four walls” of your household budget. By focusing your limited cash on shelter, food, basic utilities, and transportation, you ensure your family remains safe and functional. Once these core needs are met, you can then look at how to distribute any remaining funds to secondary creditors. It is vital to distinguish between “wants” and “needs” during this time, as even small discretionary purchases can quickly deplete your remaining cash reserves.
File for unemployment benefits the day after your job loss becomes official. These government funds take several weeks to process, so applying early provides essential cash flow during your transition.
After securing your basic needs, you can evaluate how to allocate any remaining funds to your creditors. If you have trouble paying everything, focus on secured debts like your mortgage or your monthly car payments first. Falling behind on these secured obligations risks the immediate loss of your family home or your primary vehicle. Unsecured debts, while important, do not carry the same immediate risk of asset seizure as your primary residence or transportation.
Contact Your Creditors Before Missing Payments Due to Job Loss
Ignoring your financial obligations can lead to fees, collections, and serious credit damage. Instead, contact your lenders early, explain your situation, and ask about hardship programs. These options are often not advertised, so request the hardship department directly.
Call the number on your billing statement and ask about lowering interest rates or waiving fees. This shows responsibility and helps protect your credit score. Many lenders may offer temporary relief, such as short forbearance periods, if you’re actively seeking work.
Keep records of every conversation with your lenders. Note names, dates, and any agreed-upon terms to avoid disputes later. Whenever possible, request written confirmation for your records.
- Assess your liquid cash and emergency savings immediately to understand your baseline financial reality.
- Prioritize basic living expenses and health insurance coverage over standard unsecured debt payments.
- Contact lenders proactively to request placement in temporary hardship programs before missing any payments.
How to Handle Debt After Losing Your Job: Managing Specific Obligations
Handling Credit Card and Unsecured Debts
Monthly credit card bills represent a massive source of anxiety when your regular paychecks suddenly stop arriving. These unsecured debts often carry exceptionally high interest rates that cause your outstanding balances to grow rapidly. You should request formal forbearance or a temporary reduction in your minimum payment requirements from your credit card issuer. If they refuse a full forbearance, ask if they can move your payment due date to align with your unemployment check arrivals.
If you hold multiple credit cards, focus your highly limited funds on the specific account carrying the highest interest rate. You must stop using your credit cards for daily purchases unless necessary for your basic survival. Accumulating additional credit card debt during a period of unemployment only prolongs your eventual financial recovery process. Consider hiding your physical cards or removing them from digital wallets to prevent impulsive spending during stressful moments.
Dealing With Student Loan Repayment
Managing student loan debt requires a completely different approach depending on the specific type of loan you hold. If you have a federal student loan, you have access to robust legal protections through established government programs. You can apply for an income-driven repayment plan that could drop your required monthly obligation to zero dollars. This adjustment is based on your current income, which is effectively nonexistent during a period of unemployment.
Contact your designated loan servicer immediately to discuss deferment or forbearance options for your federal student accounts. Conversely, a private student loan typically offers far fewer consumer protections and significantly less flexible repayment alternatives. You must negotiate directly with your private student lender to find a workable short-term solution for your private student loans. Some private lenders may offer a “graduated repayment” option that lowers payments temporarily while you are between jobs.
Managing Auto Loans and Personal Loans
Auto loans require special attention because losing your vehicle often means losing your ability to commute to a new job. If you find yourself unable to make the full payment, contact the lender to discuss a loan extension or a temporary payment deferral. Most lenders prefer to modify your existing terms rather than deal with the expensive and time-consuming process of vehicle repossession. They may allow you to skip one or two payments and add them to the end of the loan term.
Personal loans from banks or online lenders should be handled with similar transparency and proactive communication. Explain your situation clearly and ask if they offer interest-only payment options for a limited duration. Maintaining an open dialogue prevents the lender from sending your account to a third-party collection agency prematurely. If you have a co-signer on any of these loans, be sure to inform them of your situation so they are not blindsided by a sudden drop in their own credit score.
Explore Long-Term Debt Relief Options After Job Loss
If unemployment lasts for months, temporary relief programs may expire. At this point, formal debt relief options can help manage growing obligations. It’s important to balance their impact on your credit with the need for financial stability.
For former business owners, separate personal and business debts as soon as possible. This helps protect your personal credit from business-related issues. A financial advisor can guide you through closures, restructuring, and any personal guarantees.
Debt consolidation can simplify payments and potentially lower interest rates. However, qualifying without a steady income can be difficult unless applying jointly with someone employed. Another option is a debt management plan, where agencies negotiate terms, though it may require closing credit accounts.
Avoid any debt settlement company that demands large upfront fees before performing actual negotiation services. Unregulated debt settlement severely damages your credit report and may trigger unexpected tax liabilities on any forgiven balances.
Protect Your Identity and Credit Score
During a stressful financial transition, you must remain highly vigilant against external threats to your personal data. Scammers frequently target vulnerable individuals who post resumes online or discuss their sudden termination on social media platforms. You must stay safe online and carefully evaluate any unsolicited offers for emergency loans or immediate employment. Many of these “too good to be true” offers are actually phishing attempts designed to steal your remaining funds.
Protecting your online privacy helps prevent malicious actors from opening unauthorized credit accounts in your specific name. Identity theft creates disastrous legal complications when you are already struggling to manage your legitimate financial obligations. Always verify the legitimacy of potential employers or private lenders before sharing your highly sensitive personal information. Use multi-factor authentication on all your financial accounts to provide an extra layer of security against unauthorized access.
In addition to monitoring your credit, consider placing a temporary fraud alert on your credit files with the major bureaus. This extra layer of security requires lenders to verify your identity more rigorously before granting any new credit in your name. Taking these preventive measures reduces the risk of long-term damage to your financial reputation during an already difficult period. A fraud alert is free and stays on your credit report for one year, providing peace of mind while you focus on your job search.
You should monitor your credit report regularly to catch any highly suspicious financial activity as early as possible. Federal law allows you to request free weekly reports from the three major consumer credit bureaus via AnnualCreditReport.com. Reviewing these official documents helps you stay safe and maintain absolute control over your ongoing financial narrative. If you spot an error, dispute it immediately to ensure your credit score remains as high as possible for future lenders.
- Leverage federal protections for student loans by immediately applying for income-driven repayment plans.
- Consider professional credit counseling for a structured management plan if your unemployment persists.
- Monitor your credit reports closely to detect and prevent identity theft during your active job search.
Conclusion
Managing debt after a job change requires clear communication and disciplined spending. While it can feel overwhelming, small, consistent steps can lead to stability. With the right approach, you can protect your credit and recover over time.
Once you find new employment, focus on rebuilding your emergency fund. Aim to save three to six months of essential expenses for future security. This safety net helps you handle unexpected financial challenges more confidently.
Long-term success depends on staying flexible and maintaining a realistic outlook. Use available resources and stay informed to manage your obligations effectively. Your discipline now will lead to greater financial stability and freedom later.