Money fights consistently rank among the top reasons couples file for divorce in the United States. Learning how to manage debt as a couple when you have different spending habits requires merging entirely different backgrounds, values, and daily habits regarding personal finance. Effective money management for partners involves more than just spreadsheets; it requires emotional intelligence. One partner might love the thrill of a spontaneous purchase, while the other prefers hoarding cash.
Managing shared debt as a couple requires extreme patience, especially when opposing financial personalities inevitably collide. You cannot simply force a natural spender to become an aggressive saver without causing serious resentment. Long-term success demands open communication, structural compromises, and a mutual commitment to achieving permanent financial stability.
Before you can tackle the numbers, you must address the emotional weight of your financial situation. A study by the American Psychological Association found that many adults report money as a major relationship stressor. Ignoring this obvious financial friction only allows dangerous resentment to build between partners over a long period.
Different spending habits do not automatically doom a romantic relationship to failure or eventual divorce proceedings. Many highly successful couples leverage their contrasting views to balance each other out over the decades. The saver protects the family from financial ruin, while the spender helps the couple enjoy life.
High-interest debt complicates this natural personality dynamic significantly for almost every modern American household today. When massive credit card balances enter the picture, casual spending differences quickly escalate into serious trust issues. You must view the debt as a shared enemy rather than pointing fingers at your spouse.
- Debt is a shared household problem, regardless of which partner accumulated the original balance.
- Contrasting financial habits can actually create a balanced partnership if managed with mutual respect.
- Ignoring financial disagreements inevitably leads to deep resentment and long-term relationship damage.
Achieving Financial Compatibility: Understand Your Money Scripts
Psychologists use the term money scripts to describe the unconscious beliefs we hold about personal finances. We typically develop these core beliefs during childhood based on how our parents handled household income. Achieving long-term financial compatibility involves identifying these underlying motivations to help depersonalize financial disagreements during tense conversations about your monthly budget.
Identifying these underlying motivations helps depersonalize financial disagreements during tense conversations about your monthly budget. If your partner buys expensive clothes, they might be fulfilling a deep-seated need for social acceptance. Recognizing the root cause changes the conversation from an aggressive accusation to a peaceful exploration.
Have an honest discussion about your earliest financial memories before you start analyzing your bank statements. What did money mean in your household growing up as a young child or teenager? This vulnerability builds empathy and creates a solid foundation for the difficult debt conversations ahead.
Schedule your financial conversations during calm periods rather than immediately after discovering an unexpected credit card charge.
Avoid Financial Infidelity: Lay Everything on the Table
Transparency acts as the ultimate antidote to financial anxiety within any committed romantic relationship or marriage. You cannot build a functional plan if either partner hides credit card balances or personal loans. Financial infidelity destroys mutual trust faster than almost any other relationship hurdle you will ever face.
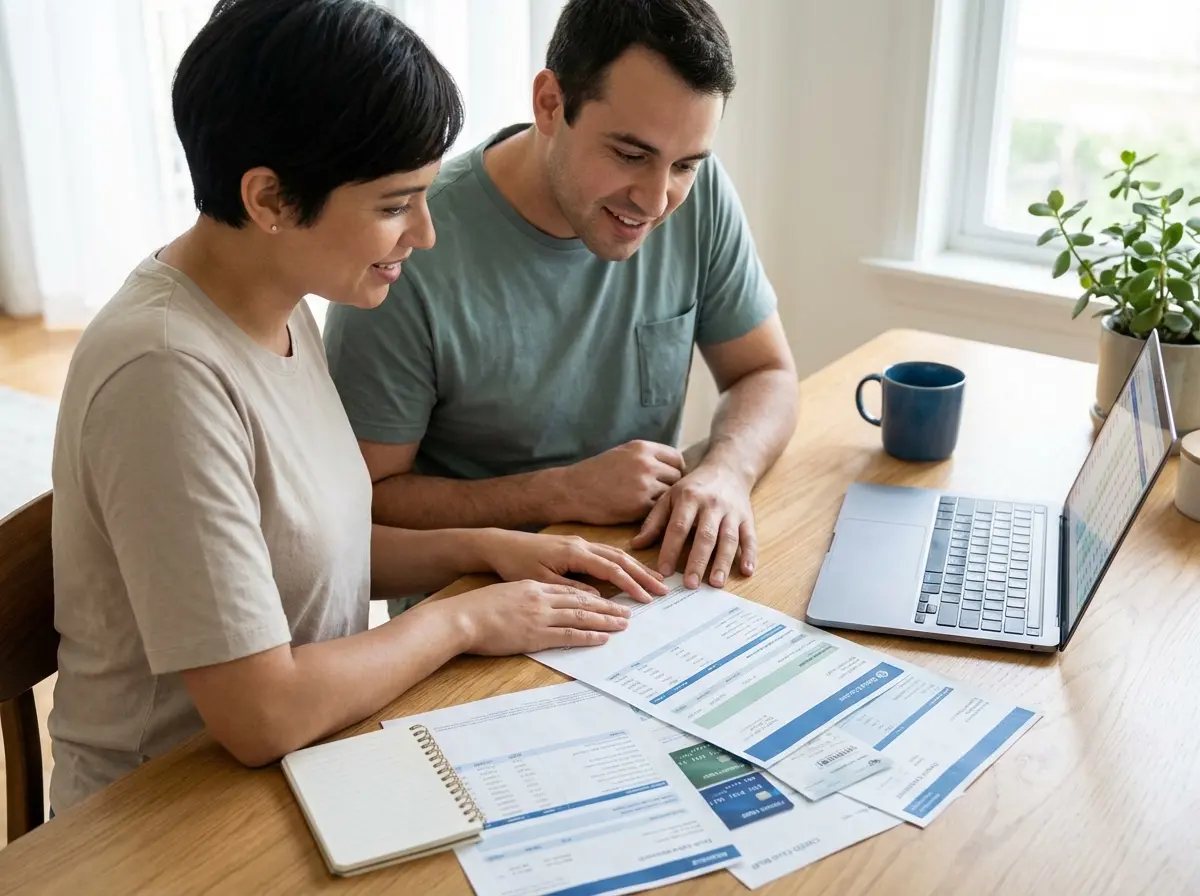
Schedule a dedicated time to review all financial accounts together in a quiet, distraction-free environment. Bring every paper statement, digital login credential, and recent credit report to the kitchen table. Create a neutral, judgment-free zone where both partners feel completely safe disclosing their true financial status.
Document every single active liability in a shared spreadsheet that you both can access easily. List the total balance, minimum monthly payment, and interest rate for each individual credit account. You need a complete, highly accurate picture of your total debt burden before taking action.
How to Audit Your Shared Debt
Pull Your Credit Reports
Retrieve free copies of your credit files to identify all active accounts and hidden balances.
List All Balances
Document the exact amount owed on every single personal loan, student loan, and credit card.
Calculate Net Worth
Subtract your total liabilities from your total assets to find your actual starting point.
Proven Debt Payoff Strategies: How to Manage Debt as a Couple When You Have Different Spending Habits
Once you know exactly what you owe, you must decide how to attack the outstanding balances. Two popular debt payoff strategies dominate personal finance circles today: the debt snowball and the debt avalanche. The snowball method focuses on paying off the smallest balances first to build immediate psychological momentum.
The avalanche method targets the highest interest rates first, which mathematically saves the most money overall. Couples with conflicting habits often benefit from the snowball method because the quick wins sustain motivation. Discuss both options thoroughly and select the specific framework that best fits your combined psychological needs.
You also need to decide exactly how to structure your joint bank accounts and individual accounts to maintain personal autonomy while working for shared financial goals. Many couples use a hybrid method to maintain personal autonomy while working for shared financial goals. You deposit joint funds for bills, leaving the remainder in individual accounts for personal discretionary spending.
Never close an old credit card account immediately after paying it off without checking your credit score impact first.
Budgeting for Couples: Build a Compromise Budget for Effective Debt Management
A rigid, highly restrictive budget will inevitably fail if one partner naturally inclines to spend money. You must build a flexible financial framework that comfortably accommodates both of your distinct personality types. Utilizing the best budgeting apps for couples can help you aggressively target debt reduction without completely eliminating discretionary purchases.
Allocate a specific fun money category for each partner every single month without fail. This money comes with absolutely no strings attached and requires no explanation to the other person. Providing this controlled outlet prevents the spending partner from feeling trapped and abandoning the financial plan.
Automate your financial systems as much as possible to remove the heavy burden of constant decision-making. Set up automatic transfers for your minimum debt payments and your extra principal reduction contributions. Automation reduces the chances of starting a bitter fight over how to spend leftover cash.
Shared Financial Goals: Track Progress and Adjust Your Debt Payoff Strategies
Financial plans require constant maintenance and frequent adjustments to remain highly effective over long periods. You should schedule a regular money date once a month to review your collective progress and refine your debt payoff strategies. Treat this specific meeting as a high-priority professional appointment that cannot be easily skipped or canceled.
Review your debt spreadsheet during these meetings to celebrate the outstanding balances actively going down. Acknowledging your collective progress reinforces positive behavior and keeps both partners highly engaged in the process. If a specific budget category constantly runs over, adjust the underlying numbers rather than placing blame.
Remember that life happens, and totally unexpected expenses will occasionally derail your debt payoff timeline. A Federal Reserve report showed many Americans cannot cover a minor emergency expense using cash. Maintain a small emergency fund even while paying down debt to prevent new financial crises.
- Establish a set fun money allowance to satisfy the spending partner without derailing the budget.
- Automate your debt payments to eliminate monthly arguments over how to allocate leftover cash.
- Schedule regular financial meetings to track your progress and adjust spending categories as needed.
Managing Shared Debt: Address the Emotional Toll of Financial Stress and Debt
Carrying significant consumer debt places an enormous psychological burden on both individuals within a committed relationship. The constant worry about making minimum payments can easily lead to sleepless nights and chronic anxiety. These mental health struggles often spill over into other areas, causing arguments over entirely unrelated issues.
You must actively monitor your partner for clear signs of financial burnout during your payoff journey. If the aggressive saver pushes the budget too hard, the spending partner will eventually crack. Maintaining a healthy romantic relationship matters far more than paying off a credit card slightly early.
Schedule regular check-ins that focus strictly on personal feelings rather than numbers or spreadsheet calculations. Ask your partner how they feel about your current lifestyle restrictions and listen without interrupting. Validating their emotional experience builds deep trust and keeps you united against the actual financial problem.
Handling Credit Card Debt: Navigate Income Disparities and Shared Debt Ownership
Discussions about debt become increasingly difficult when one partner earns significantly more money than the other. The higher-earning individual might feel resentful if forced to pay off obligations they did not accumulate. Conversely, the lower-earning partner often feels completely powerless and guilty about dragging their spouse down financially.
You must separate your personal self-worth from your calculated net worth to survive this challenging dynamic. Marriage legally and practically binds your financial futures together, regardless of who signed the loan documents. Treat all income as household money and view all debts as a collective household liability.
Resist the immense temptation to keep score or use past financial mistakes as ammunition during arguments. The spender must take accountability for their past choices, but the saver must offer genuine forgiveness. Moving forward requires a clean slate and a shared vision for your upcoming financial milestones.
Expert Money Management: Seek Professional Guidance for Complex Financial Goals
Sometimes, deeply ingrained spending differences run too deep for a married couple to resolve on their own. Are you constantly fighting about every single credit card transaction that appears on your monthly statement? If money conversations consistently end in screaming matches, you might need professional outside intervention from a financial therapist immediately.
Consider hiring a fee-only financial planner or a highly specialized, licensed financial therapist for guidance. Financial therapists specialize in the intersection of human psychology and money, making them ideal for couples. They help uncover the hidden emotional triggers driving harmful financial behaviors and excessive consumer spending.
Credit counseling agencies also offer incredibly valuable resources for couples overwhelmed by massive consumer debt. The National Foundation for Credit Counseling provides access to certified counselors who can help you. Do not let foolish pride stop you from getting the professional help your relationship desperately needs.
Conclusion
Merging a strict saver and a natural spender into a cohesive financial unit takes significant effort. You will face frustrating setbacks, intense arguments, and moments of severe doubt along the way. However, mastering this specific challenge builds a resilient partnership capable of handling almost any future obstacle.
Focus heavily on your shared financial goals for the future rather than obsessing over individual retail transactions. Whether you want to buy a house, start a family, or travel extensively, eliminating debt helps. Keep that ultimate objective at the absolute forefront of every financial decision you make together.
Managing debt as a couple requires deep mutual respect and a constant willingness to compromise. The spender must learn basic discipline, while the aggressive saver must learn necessary lifestyle flexibility. By working as a unified team, you can eliminate your financial burdens and build wealth together.